Skip to content
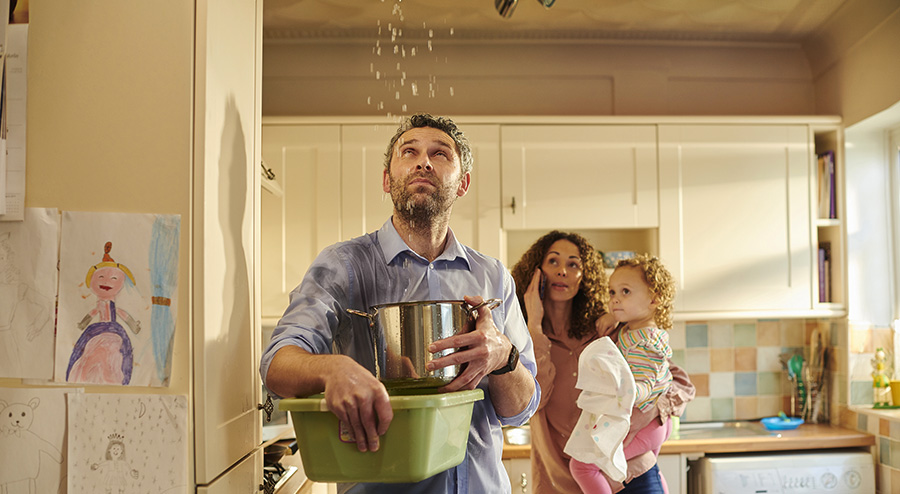
A pipe bursts in the bathroom. The dishwasher leaks while you’re away. Heavy rainfall causes a sewer backup. Water seeps through the roof or enters through the basement windows.
In every case, the result can look much the same: water on the floor and potentially extensive damage.
But when it comes to home insurance, not all types of water damage are covered in the same way.
So the question isn’t simply, “Do I have home insurance?” but rather, “Where is the water coming from, and what coverage does my policy include?”
A Burst Pipe: Generally Covered
Let’s start with a fairly common scenario.
A pipe suddenly bursts inside your home, damaging the floors, walls, or personal belongings. This type of accidental water damage is generally covered by home insurance, subject to the coverage and exclusions outlined in your policy.
The same applies to certain sudden leaks from plumbing fixtures or household appliances, such as a dishwasher or washing machine.
However, keep in mind that insurance is designed to cover sudden and accidental events, not to replace regular home maintenance.
A leak that develops gradually over several months due to a known problem or lack of maintenance may therefore be treated very differently.
What If Water Backs Up Through the Sewers?
This is where the distinction becomes particularly important.
During heavy rainfall, sewer systems can become overloaded, causing wastewater to back up into a home’s basement.
However, sewer backup coverage isn’t necessarily included automatically in every home insurance policy.
It may be available as additional coverage, depending on the insurer, the type of property, and the level of risk.
This is exactly the kind of detail you’d rather discover while reviewing your policy with your broker than while watching water rise in your basement.
Water Entering Through Doors and Windows
Now imagine an exceptionally heavy rainstorm. Water accumulates around your home and eventually enters through a door, window, or opening at ground level.
Once again, you shouldn’t assume that the coverage is automatically the same as it would be for a burst pipe.
Insurance policies may offer different types of protection against water entering from outside, depending on how it gets into the building.
And when we’re talking about an actual flood, such as the overflow of a river, lake, or other body of water, specific coverage may also be required.
What About Water Coming Through the Roof?
Here’s another important distinction.
If a storm suddenly damages your roof and rainwater subsequently enters your home, the resulting damage may be covered, depending on the circumstances and your policy.
However, if water has been seeping in for a long time because of a deteriorating roof, an unrepaired seal, or a maintenance issue, the situation is different.
That’s why the source of the damage and the circumstances surrounding it are so important when filing an insurance claim.
Has Your Basement Changed? Your Insurance Might Need an Update Too
A few years ago, your basement may have been nothing more than a storage area with a concrete floor.
Today, it might include a family room, home office, bathroom, home theatre, and furniture.
The financial consequences of water damage are obviously no longer the same.
The same applies if you’ve completed renovations, added a basement bathroom, or transformed part of your home since purchasing your insurance policy.
These changes are an excellent reason to review your coverage periodically with your insurance broker.
A Few Minutes Today Could Prevent an Unpleasant Surprise Tomorrow
We often assume we’re simply “insured against water damage.” In reality, home insurance is much more nuanced.
Burst pipes, water infiltration, sewer backups, groundwater, overflowing rivers or lakes: where the water comes from can make all the difference in determining which coverage applies.
And since policies, coverage options, and exclusions can vary from one insurer to another, it’s best not to assume that everything is covered.
Your insurance broker at Assurances Groupe Vézina can review your home insurance coverage with you and clearly explain what’s covered… and what might require additional protection.
Because when it comes to water damage, the best time to ask questions is while your basement is still nice and dry.